Please welcome guest contributor Janis Bergman who has some helpful advice about retirement!
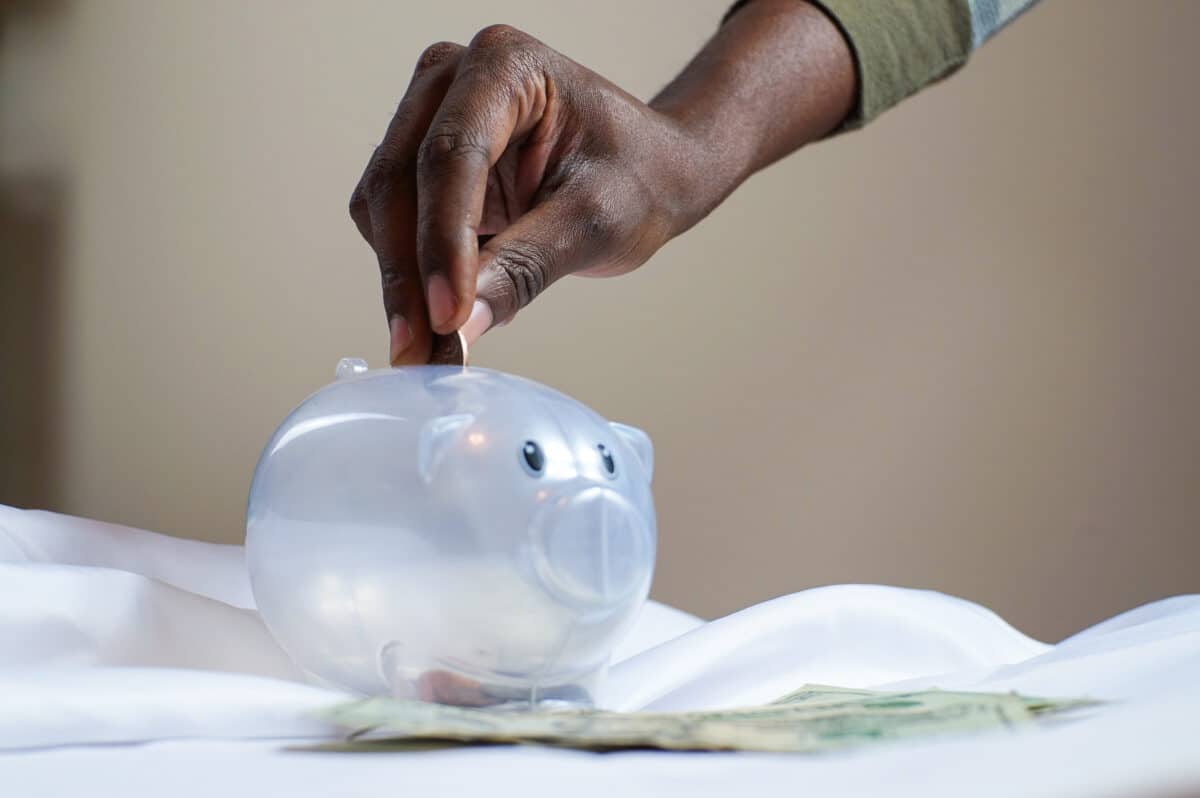
According to a 2017 report by the Government Accountability Office (GAO), presented on Yahoo the average retirement saving amount for Americans aged 55 to 64 was just over $107,000. The GAO estimates that this would give them a meager $310 to live on per month without a steady income to supplement it. And as life expectancy, medical expense rates, and inflation all rise, insufficient retirement savings might lead to a lower quality of life as one ages. Below are a few things you need to know if you want to prepare for retirement.

Retirement accounts are not one-size-fits-all
You can grow your investments at a tax-advantaged rate with retirement accounts like 401(k)s and IRAs. How much you allocate in each account depends on your employment situation.
You’d benefit most from a 401(k) plan if your employer offers a contribution match. For example, your employers might promise a 100% match on contributions that amount to 3% of your salary, doubling your potential for returns. However, the downside of a 401(k) is that you’d be limited to the small selection of stocks, bonds, and mutual funds your employer makes available to you. If your company’s 401(k) plan doesn’t offer contribution matches, you can place money in an IRA, which offers a larger selection of investments. IRAs, however, have a much lower contribution limit, which can restrict your wealth’s growth.
You also need to choose between pre-tax benefits and after-tax benefits. Pre-tax accounts will allow you to deduct your contributions from your payable tax at the cost of making your future withdrawals taxable. On the other hand, after-tax accounts like the Roth IRA and the Roth 401(k) take contributions from your post-tax income, but charge no tax on retirement withdrawals.
Saving for medical expenses is a must
As you age, your body becomes less adept at protecting you from disability or disease. If you have a high deductible health plan, you can build a fund for future medical expenses by contributing to a Health Savings Account. Like retirement accounts, contributions made to HSAs are tax-deductible, and because your earnings are used for eligible medical expenses, your withdrawals cannot be taxed.

You need to plan for inflation
It’s estimated that maintaining your pre-retirement lifestyle requires you to have 80% to 100% of your current annual income each year that you’re retired. If you’re currently earning $80,000 annually, and you want to live on 80% of that while retired, you’d need to save enough to generate $64,000 a year.
However, due to inflation, the $64,000 you have in your 60s will not have the buying power it did in your 30s. An article on inflation by Marcus even argues that placing your money in a savings account won’t grow it enough to compete with inflation. This is because inflation rates in the US rise by about 2% a year, while APYs for traditional savings accounts have an average of 0.06%. Since inflation cancels out the slow growth of wealth under traditional savings methods, you need to compute for inflation when planning how much you need in your retirement pot.
Diversification is key — but so is your risk tolerance
If you have a lot of time between now and retirement, you can afford to be more aggressive in your investment strategy. Not only does long term-investment give your money more than enough time to recover from any market downturns, it also gives it more time to compound.
To optimize your portfolio, combine high-risk assets that generate high returns with low-risk, low-return assets that protect your wealth. For instance, stocks and gold generally follow opposing trends. Additionally, in our ‘Best Advice: Investing’ column, we note that stocks are not the only option for investors. If you want a to reduce the effort of picking individual securities yourself, you can invest in mutual funds or ETFs for a basket of asset classes. Essentially, they do the work of diversifying your portfolio for you.
The loss of major sources of income during retirement can be daunting. If you want to enjoy your senior years without worrying about labor, invest wisely to build your retirement fund.
Discover more from The Cameron Journal
Subscribe to get the latest posts sent to your email.