Key Takeaways
- A strong financial plan balances immediate access to money with long-term growth potential.
- The right cash reserve depends on income reliability, expenses, debt, family needs, and employment stability.
- Cash works best when it is divided into intentional categories rather than held in a single, unplanned pool.
- Every financial option involves trade-offs among access, risk, cost, tax implications, and expected growth.
- A cash plan should be reviewed after major life changes and at least once a year.
Financial confidence is not only about how much money a household earns or invests. It is also about having the right money available at the right time. A thoughtful cash flow banking system can help organize everyday spending, emergency reserves, and long-term assets so that one financial goal does not undermine another.
In 2026, rising costs, variable income, debt obligations, and changing family needs make liquidity planning especially important. The goal is not to keep every dollar in cash or to lock every dollar into long-term accounts. It is to assign each dollar a purpose based on when it may be needed and what level of risk is appropriate.
Why Cash Reserves Matter
A cash reserve is money set aside for unplanned expenses, income interruptions, or near-term obligations. It can cover a vehicle repair, a medical deductible, a broken appliance, a home repair, or a temporary loss of work. Households that maintain a dedicated emergency fund may be less likely to rely on high-interest credit cards, personal loans, or premature withdrawals from retirement accounts.
Consider a household that faces an unexpected $4,000 furnace repair. Without savings, the family may need to finance the repair, adding interest costs to an already stressful event. With a properly funded reserve, it can pay the bill, gradually restore the reserve, and avoid disrupting investments intended for distant goals.
How Much Cash To Keep
There is no universal emergency fund number. A household with secure salaries, low fixed expenses, and strong access to other resources may need a different reserve than a self-employed household with children, a mortgage, and uneven monthly revenue.
Build A Starting Target
A practical starting formula is:
Core monthly expenses × target number of months = starting reserve goal
Core expenses may include housing, utilities, groceries, insurance, transportation, minimum debt payments, and essential medical costs. Then adjust the number of months based on job stability, income variability, health needs, dependents, homeownership, vehicle costs, business responsibilities, and reliable backup resources. The target should evolve when expenses or responsibilities change.
How To Review Personal Cash Flow
Liquidity problems are often timing problems. A household can have enough annual income on paper but still experience a shortage when several bills arrive before the next paycheck. Reviewing cash flow means looking beyond a basic monthly budget.
- List dependable income sources and their expected payment dates.
- Separate fixed bills from flexible spending.
- Identify annual, seasonal, and irregular expenses.
- Mark months with higher costs, such as insurance renewals, school expenses, travel, taxes, or repairs.
- Track debt payments, interest rates, and payoff timelines.
- Set a realistic savings amount for each pay period.
This process reveals whether a reserve is being used for genuine emergencies or predictable costs that should have their own sinking fund. Planning ahead for known expenses protects the emergency reserve from being drained repeatedly.
How To Divide Money By Access
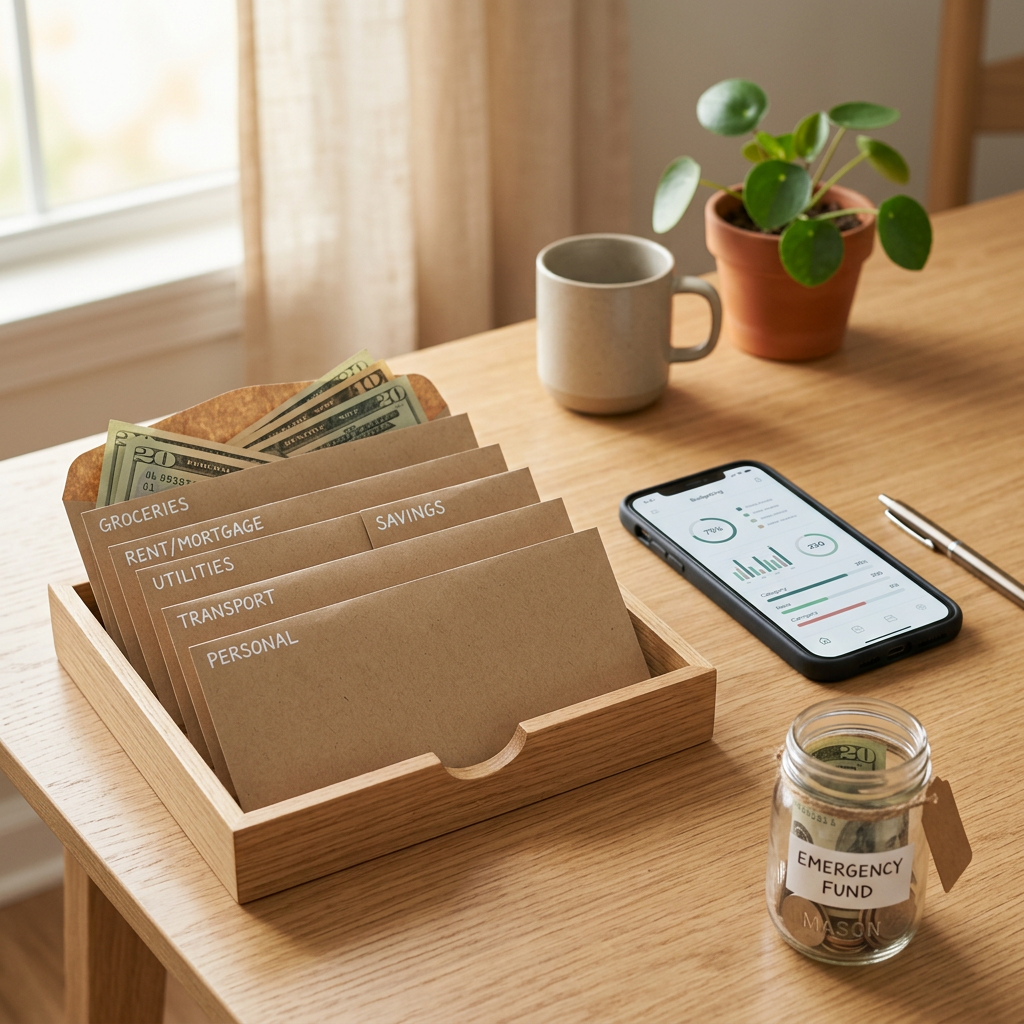
Assigning distinct roles to money can reduce confusion and improve decision-making. A simple tiered structure often includes three levels:
- Immediate cash: Funds for regular bills, small surprises, and urgent needs.
- Short-term reserves: Money for planned expenses within roughly one to three years, such as a vehicle replacement, home project, or tuition payment.
- Long-term assets: Resources intended for retirement, education, business growth, legacy goals, or other objectives many years away.
Keeping every dollar in cash may reduce market volatility, but it can limit long-term purchasing power. Conversely, allocating every available dollar to long-term assets can create pressure to sell during a downturn or to borrow at unfavorable rates. The appropriate mix depends on the purpose and time frame for the money.
How To Compare Financial Options
Savings accounts, certificates of deposit, taxable investments, credit lines, and insurance-based arrangements should be evaluated by function rather than marketing language. Before choosing any option, ask:
- How quickly can funds be accessed? Emergency money should not require a lengthy sales or approval process or a penalty.
- Can the value decline? Market fluctuations may be unsuitable for money needed soon.
- What fees, charges, or interest costs apply? Costs can materially reduce results over time.
- Are taxes or penalties possible? Withdrawals, sales, and policy changes can have consequences.
- What happens if contributions stop? Some strategies require ongoing funding to work as intended.
- Does it match the goal? The best tool is one that fits the time horizon, risk tolerance, and need for access.
Where Insurance-Based Tools May Fit
Permanent life insurance can be part of a broader plan for people with a lasting insurance need, but it is not a universal replacement for emergency savings or straightforward investing. Its primary purpose should be the protection of beneficiaries. Cash value, when available, is a feature that requires careful review rather than an automatic reason to buy a policy.
Policy design, premiums, insurer strength, surrender terms, withdrawals, and loans can all affect available value. Readers considering variable policies should carefully review fees, loans, lapses, and tax consequences before treating policy cash value as a source of short-term liquidity. Guaranteed values and non-guaranteed illustrations should always be considered separately.
Common Risks And Mistakes
- Holding too little cash for known or likely expenses.
- Keeping excessive cash without considering inflation and missed growth opportunities.
- Confusing an account balance with the amount that is immediately available after costs or taxes.
- Ignoring fees, surrender charges, loan interest, and tax rules.
- Using long-term investments to fund routine short-term spending.
- Relying on projected returns instead of understanding guarantees and downside risk.
- Failing to update the plan after a job change, marriage, divorce, birth, move, or business purchase.
A Simple 2026 Action Plan
- Calculate essential monthly expenses.
- List major anticipated bills for the next 24 months.
- Set a starting reserve target based on personal circumstances.
- Keep emergency funds in a safe, accessible location.
- Review long-term accounts and the risks associated with each.
- Compare insurance-based strategies with simpler alternatives.
- Automate contributions when cash flow permits.
- Schedule an annual review, particularly when finances involve a business, estate plan, or complex tax considerations.
Final Thoughts
A useful cash strategy does more than prepare for surprise bills. It connects today’s spending with tomorrow’s priorities. By separating immediate needs, short-term reserves, and long-term assets, households can make clearer choices without forcing one account to do every job. The best plan is usually not the most complicated one. It is the plan that fits the household, remains affordable, and can adapt as life changes.
Discover more from The Cameron Journal
Subscribe to get the latest posts sent to your email.