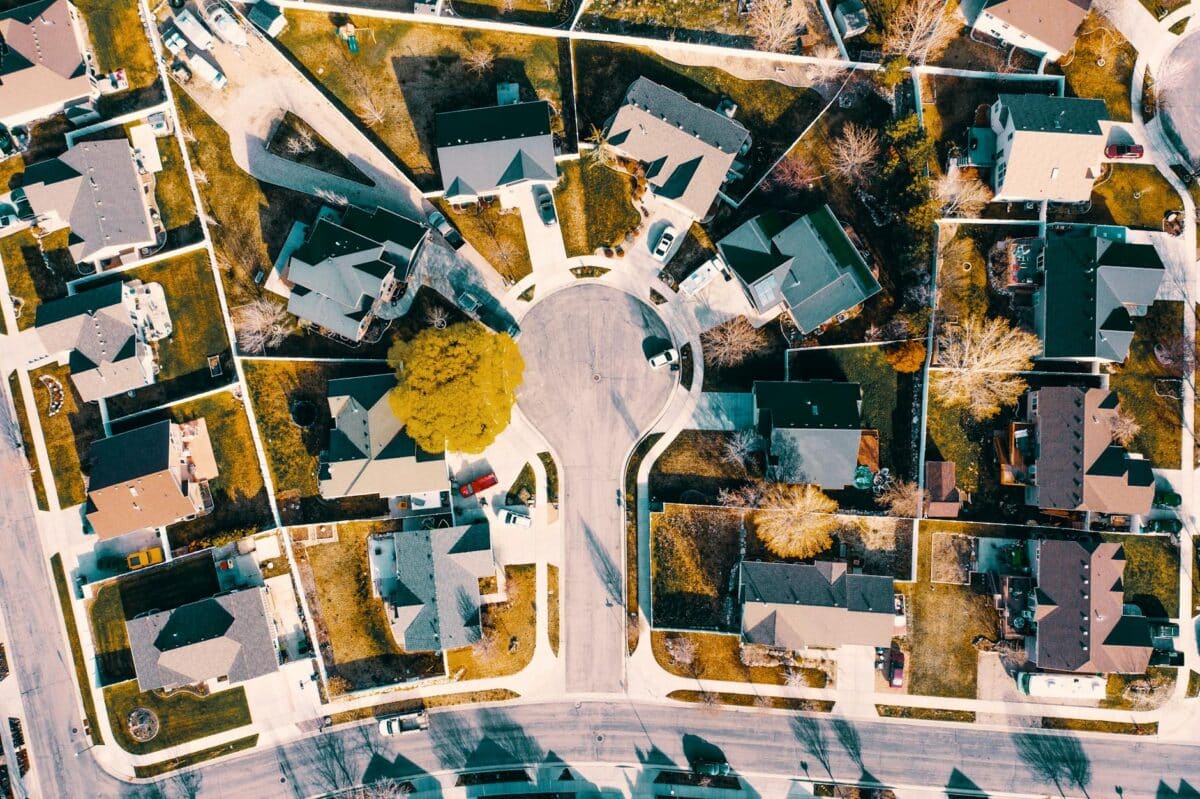
With just 32% of home purchases last year made by first-time buyers, compared to the historical average of 40%, the personal-finance website WalletHub today released its report on the Best & Worst Cities for First-Time Home Buyers in 2024, as well as expert commentary, to identify where people stand to save the most money and enjoy the best living conditions.
WalletHub took the pulse of real estate in 300 cities of varying sizes using 22 key metrics. The data set ranges from housing affordability to the real-estate tax rate to the crime rate.
| Best Cities for First-Time Home Buyers | Worst Cities for First-Time Home Buyers | |
| 1. Palm Bay, FL | 291. New York, NY | |
| 2. Cape Coral, FL | 292. Costa Mesa, CA | |
| 3. Port St. Lucie, FL | 293. Glendale, CA | |
| 4. Tampa, FL | 294. Los Angeles, CA | |
| 5. Orlando, FL | 295. San Francisco, CA | |
| 6. Surprise, AZ | 296. Oakland, CA | |
| 7. Lakeland, FL | 297. Santa Barbara, CA | |
| 8. Boise, ID | 298. Anchorage, AK | |
| 9. Gilbert, AZ | 299. Santa Monica, CA | |
| 10. Henderson, NV | 300. Berkeley, CA |
Best vs. Worst
- Detroit, Michigan, has the most affordable housing (median house price divided by median annual household income), which is 10.4 times cheaper than in Santa Barbara, California, the city with the least affordable housing.
- Honolulu has the lowest real-estate tax rate, which is 11 times lower than in Waterbury, Connecticut, the city with the highest.
- Flint, Michigan, has the highest rent-to-price ratio, which is 14.2 times higher than in Santa Monica, California, the city with the lowest.
- Baton Rouge, Louisiana, has the lowest total home-energy cost per month, which is 3.4 times lower than in Bakersfield, California, the city with the highest.
View the full report and your city’s rank
“Buying a home for the first time is a very stressful and difficult process, especially when housing prices are through the roof and interest rates have risen sharply in the past few years. The best cities for first-time home buyers not only are affordable both in terms of buying a house and living there afterward, but they also have a lot of housing choices as well as low crime rates and good schools.”
–
“Palm Bay, FL, is the best city for first-time home buyers, leading the country when it comes to active home listings per capita and new building permits per capita. Palm Bay has the third-highest millennial home-ownership rate and the fourth-highest home appreciation rate in the country. Home-buyers with children will benefit from Palm Bay’s good school system.”
– Cassandra Happe, WalletHub Analyst
Expert Commentary
What should first-time homebuyers consider when choosing a neighborhood?
“First-time homebuyers should consider several characteristics when choosing a neighborhood, based on the household’s preferences and needs. These include neighborhood density, public school quality, proximity to retail and employment, and public safety. It is important to view homebuying as a long-term decision, considering future household needs. Many people underestimate the negative effect of long commutes on the quality of life. They trade longer commutes for a larger or less expensive home. However, a large amount of economic and health research has shown that long commutes significantly harm health and happiness.”
Mike Mei – Assistant Professor, Colgate University
“While the selection of a neighborhood is often constrained by an individual’s budget, it is best to consider proximity to places they frequently visit, such as work, school, shopping, and other amenities. It is also important to consider trends in housing values as well as other characteristics that impact the cost of ownership, such as property taxes and insurance costs. For example, purchasing a home in a neighborhood where flood insurance is required can add significantly to the cost of ownership, which may be difficult for a first-time buyer to handle. Additionally, some adjacent neighborhoods may have significantly different tax burdens, so very small differences in location can have large impacts on the annual property tax bill.”
H. Shelton Weeks – Professor, Florida Gulf Coast University
How do you know that you are financially ready to buy your first home?
“If you have had a stable job for the last 2 years with foreseeable continuation, have saved enough to make at least a 10% to 20% down payment, and are ready to settle down in one location, you might be ready to purchase your first home. However, the cost of owning a home is not simply just the mortgage amount. When you prepare for your first home purchase, calculate the purchase price you can afford and set the price range realistically. This is often called the ‘Affordability Calculator’. A reverse calculation allows home buyers to foretell the type of home they can afford given a rough estimate of their current debt and monthly spending. This helps home buyers avoid overspending and avoid putting themselves into avoidable financial constraints.”
Duong Katie Pham, Ph.D. – Associate Professor, Georgia Southern University
“You are financially ready to buy your first home when you have a stable income, manageable debt, a good credit score, and sufficient savings for a down payment and closing costs. It is also important to have an emergency fund and be able to comfortably afford monthly mortgage payments, property taxes, and home maintenance expenses (6 months of coverage is a good rule of thumb).”
Dr. David Bieri – Associate Professor, Virginia Tech
Do you consider 2024 to be a good year to buy a home?
“For most Americans, unfortunately, 2024 is a very difficult year to buy a home. High interest rates and high prices are a financially challenging combination. The Federal Reserve Bank of Atlanta’s Home Ownership Affordability Monitor is down in the doldrums where it was in 2006 when prices were overinflated at the height of the big housing bubble. This time, though, lenders aren’t throwing cheap debt at the problem. Instead, buyers are stymied by a lack of affordable financing and lack of inventory. For buyers who have access to capital, it can be an opportunity – that’s why institutional investors are gobbling up homes and homebuilders are buying down rates to entice new customers – because they can find deals now before rates come down and prices go up again. And then, when the rates come down, they can refinance those expensive mortgages. But that strategy only makes sense for investors who have the liquidity to make high mortgage payments for the foreseeable future. It’s not a viable strategy for the vast majority of Americans.”
Anthony W Orlando – Associate Professor, California State Polytechnic University, Pomona
“This is a challenging year for homebuyers for several reasons. Mortgage interest rates are relatively high, and so are home prices. In many places, particularly in regions with strong economies, demand for housing outstrips supply. Investors are also competing with first-time homebuyers by purchasing housing stock for use as rentals. At the same time, awareness is growing regarding challenges faced by homebuyers. Initiatives like the relaxation of accessory dwelling unit (ADU) rules and revised zoning codes (discussed further below) are creating new opportunities that can make this a good buying year in some places.”
Krista Paulsen, Ph.D. – Professor; Interim Program Lead – Environmental Studies; Program Lead – Urban Studies, Boise State University
Discover more from The Cameron Journal
Subscribe to get the latest posts sent to your email.