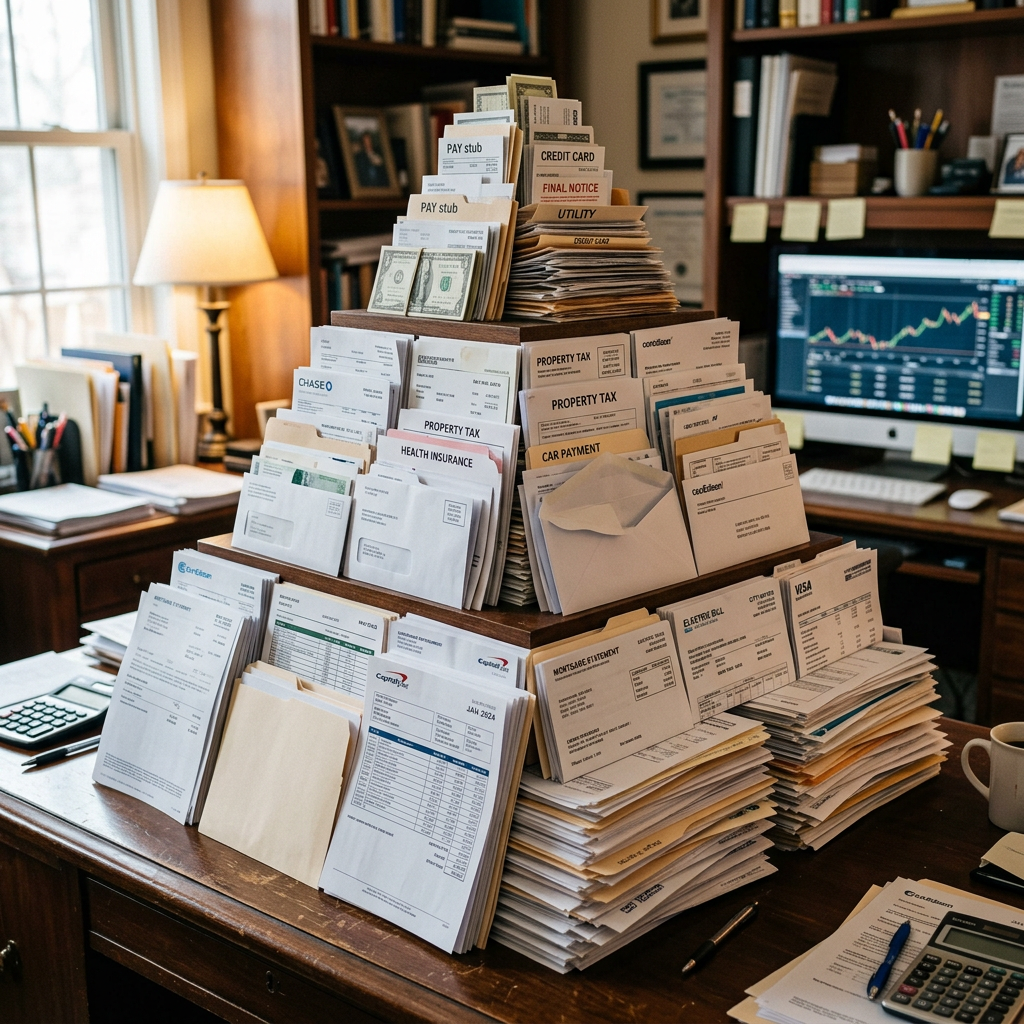
When debt feels overwhelming, most people do not actually need more motivation first. They need order. Stress has a way of making every bill look equally urgent, even when the real risk is not equal at all. That is where many debt payoff plans go off track. People throw extra money at the loudest collector, the newest statement, or the balance that happens to annoy them most, while the debts with the biggest consequences keep quietly getting worse.
A better approach is to think of debt like triage. In an emergency room, nobody treats every patient in the order they walked in. Care starts with the cases that carry the greatest immediate danger. Personal debt works much the same way. Before worrying about the perfect spreadsheet or the fastest payoff timeline, it helps to understand the debt settlement meaning behind different strategies and why some balances demand attention before others. When you rank debts by consequence instead of emotion, your next move becomes much clearer.
Why debt payoff fails without a clear order
A lot of debt advice focuses on habits, mindset, and discipline. Those things matter, but they are not the whole story. Plenty of responsible people still get buried because they are using the wrong sequence. If your plan says to attack a store credit card first while you are behind on taxes or child support, that is not discipline. That is misprioritization.
The key idea is simple. Not all debt can hurt you in the same way. Some debts can trigger foreclosure, wage garnishment, tax enforcement, or loss of essential property. Some carry such extreme interest that they can swallow your budget in weeks. Others are serious, but they usually come after those first two groups in the pecking order. Once you accept that debt is not one big pile, but several categories with different consequences, the path forward gets less chaotic.
First, protect what can do the most damage
Priority debts come first because the fallout from ignoring them can be immediate and life changing. This category usually includes your mortgage, certain tax debts, and child support. These are not just monthly obligations. They are tied to shelter, legal compliance, and family responsibilities.
If you fall behind on your mortgage, you risk losing your home. If you ignore tax debt, penalties and interest can build while collection pressure increases. The IRS also offers information on payment plans for taxpayers who cannot pay in full, which can be far better than pretending the problem will fix itself on its own. You can review the IRS page on tax payment plan options to understand what formal arrangements may be available.
Child support belongs at the top of the list for the same reason. The consequences are not just financial. They can extend into court actions, license issues, and other legal problems. This is why a clear order matters so much. Paying an extra two hundred dollars toward a credit card while a priority debt is deteriorating can be an expensive mistake.
Second, get rid of toxic debt before it multiplies
After the truly high consequence debts are stabilized, toxic debt should usually be next. This often includes payday loans, title loans, and similar products with predatory rates or aggressive fee structures. These debts are dangerous because they are designed to recycle. What looks like a short term fix can turn into a long string of renewals, fees, and rollover balances that keep draining your paycheck.
Toxic debt does more than cost money. It steals breathing room. It makes groceries, rent, and utilities harder to cover next month because so much cash is diverted into a balance that barely shrinks. A debt with a sky high annual percentage rate can undo progress everywhere else. That is why it belongs near the top of the order, even if the balance itself looks relatively small.
This is also the stage where people often need to stop and assess whether the structure of their debt is sustainable. If the budget cannot survive because of predatory loans, solving those first is not a luxury. It is the foundation for everything that follows.
Third, organize unsecured debt with a real system
Once priority debts are protected and toxic debts are being eliminated, unsecured debts usually become the main battlefield. This group often includes credit cards, medical bills, personal loans, and old collection accounts. These debts matter, but they typically come after the categories that can create the fastest legal or personal fallout.
Here is where a structured payoff method becomes useful. The avalanche method focuses on paying the highest interest rate first while making minimum payments on the rest. The snowball method focuses on the smallest balance first to build momentum through quick wins. Both can work. The best choice is often the one you can stick with long enough to finish.
What matters most is consistency. Random payments produce random results. A method creates direction. If your balances are large and your credit card rates are steep, avalanche may save more money over time. If your morale is shot and you need visible progress, snowball may help you stay engaged. The point is not to argue over which method is universally best. The point is to stop letting unsecured debt remain an unplanned cloud over your finances.
Order creates emotional relief, not just financial relief
One overlooked benefit of ranking debt correctly is psychological clarity. When people say, “I do not even know where to start,” they usually mean they are drowning in competing urgencies. A clear order cuts through that fog. It tells you which call to make first, which payment to protect first, and which balance can wait a little longer without causing the most harm.
That shift matters because financial stress often leads to avoidance. People ignore mail, silence phone calls, and delay decisions because everything feels equally bad. But when you sort debt into levels of urgency, it becomes easier to act. You are no longer trying to solve your entire financial life by Friday. You are solving the most dangerous problem first, then the next, then the next.
If you are considering bankruptcy as part of that broader picture, the United States Trustee Program explains that credit counseling must generally be completed before filing, and debtor education is a separate step afterward. Their overview of credit counseling and debtor education requirements can help you understand those basics.
What a practical debt order can look like
In real life, a clear order might look something like this. First, bring any mortgage, tax, or child support issue out of the danger zone. That may mean catching up, setting up a formal payment arrangement, or preventing further default. Second, attack payday or title loan balances with intensity because their costs can spiral fast. Third, list unsecured debts by either interest rate or balance size and follow one system until those balances are gone or resolved.
Notice what this plan does not do. It does not treat every debt as identical. It does not encourage panic payments based on who called last. And it does not assume the most stressful bill is always the most important one. Instead, it respects consequences, cash flow, and sustainability.
The smartest debt strategy is often the simplest
People often expect debt management to feel complicated, but the most useful insight is surprisingly plain. The problem is not always a lack of effort. Sometimes it is a lack of sequence. When you put debts in the right order, you protect your essentials, cut off the most financially corrosive balances, and then work through the rest with purpose.
That is what clear debt management really means. Not doing everything at once. Doing the right things first.
Discover more from The Cameron Journal
Subscribe to get the latest posts sent to your email.