
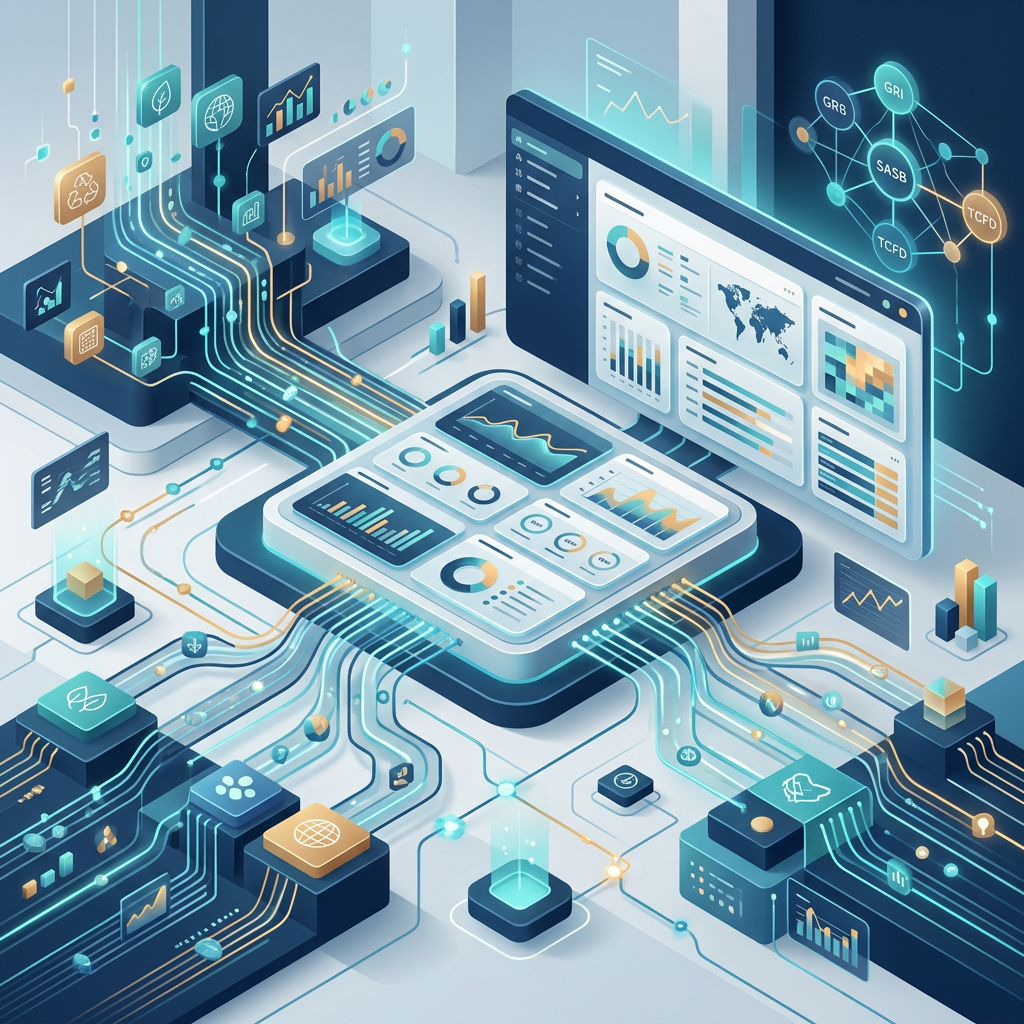
The short version: most large organisations now file to several sustainability frameworks at once, and the requirements overlap without matching.
Building a separate report for each one duplicates effort and creates inconsistencies that surface during assurance.
The alternative is structural rather than procedural. A single dataset, mapped to each framework’s requirements, removes the duplication and makes the audit trail a by-product of the reporting process rather than a separate exercise.
Key Takeaways
- Most large organisations report to multiple frameworks simultaneously, and the overlapping requirements are what make spreadsheet workflows break down.
- Mapping one dataset to every framework removes duplication and eliminates the inconsistencies that arise from parallel reports.
- Audit readiness means every figure traces back to its source, with methodology and version history captured as you go.
- CSRD currently requires limited assurance, with reasonable assurance phasing in later.
- AI is most useful for validation and drafting, and least useful as a substitute for domain judgement.
Why multi-framework reporting breaks spreadsheets
The difficulty is not the volume of data, though that is substantial. It is that CSRD, ISSB, GRI, CDP, SASB, TCFD, California SB 253 and SB 261, and the UK SRS all ask overlapping questions in different formats with different boundaries.
Answering each one separately means the same underlying figure gets restated several times, in several places, by several people.
Each restatement is an opportunity for divergence, and divergence between filings is exactly what an assurance provider looks for.
Spreadsheets compound this because they carry no inherent link between a figure and its origin.
A number in a cell looks identical whether it came from a metered reading, a supplier submission or an estimate, and six months later nobody remembers which.
The practical consequence is a reporting cycle measured in months rather than weeks. Most of that time goes on reconstructing provenance rather than analysing performance, which is the opposite of where a sustainability team adds value.
What report once, file everywhere actually requires
The phrase is straightforward, and the implementation is not. It requires a data model capable of holding one canonical value and expressing it differently for each framework that asks for it.
That means pre-built mappings from your dataset to each framework’s specific data points, with contextual guidance attached, so the person filling in a disclosure understands what is being asked.
It also means a custom layer, because most organisations track internal metrics no framework requires.
Disclosure management is the other half. Collaborative tracking and flexible approval flows matter because a filing of this size is never the work of one person, and the approval record becomes part of the evidence base.
What audit readiness means in practice
Sweep audit readiness is often described as a quality of the final report. It is more accurately a quality of the process that produced it.
The operational test is whether every figure in a disclosure can be traced back to its original input without anyone reconstructing the path from memory.
On the Sweep sustainability platform, it captures methodology and version history automatically at each step, so the lineage exists whether or not anyone anticipated needing it.
Three things make that work. Full data lineage from raw input to filed disclosure, governance workflows that record who approved what and when, and an auditor access interface that gives third-party reviewers controlled visibility rather than a folder of exported files.
The regulatory context matters here. CSRD requires limited assurance of sustainability disclosures today, with a pathway to reasonable assurance as requirements phase in, which raises the standard of evidence a reporting process has to meet.
Where AI helps, and where it does not
Domain-specific AI is genuinely useful at particular points in the reporting cycle, and overstated at others.
The useful applications share a characteristic: they accelerate work a human would otherwise do slowly, without replacing the judgement that work requires.
Validation is the clearest case. Automatically checking a dataset for errors, gaps, and inconsistencies before disclosure catches problems while they are still cheap to fix, rather than when an auditor raises them.
Drafting is the second. Generating disclosure narrative from live data gives a reporting team something to edit rather than something to write from scratch, which is a meaningful difference across hundreds of data points.
What AI does not do is decide what is material to your business, interpret an ambiguous requirement, or take responsibility for a filed disclosure. Those remain human decisions, and any tool positioning otherwise is worth scrutinising.
Building the data foundation
Everything above depends on centralised data, which is the part organisations most often underestimate.
Emissions and ESG data originate in systems that were never designed to produce disclosures.
The integration work covers ERP, HR, energy, procurement and travel systems, usually through connectors and APIs rather than exports.
Supplier portals handle the value chain data that Scope 3 reporting requires, which cannot be pulled from internal systems at all.
Version control on every figure and narrative is the detail that separates a data foundation from a data repository. Without it, a centralised dataset is simply a larger spreadsheet with the same provenance problem.
Conclusion
The shift worth making is from treating each framework as a separate project to treating disclosure as an output of a single, well-governed dataset.
That reframing is what makes multi-framework reporting sustainable as requirements continue to expand.
For teams currently rebuilding reports each cycle, the practical starting point is auditing provenance rather than adding capacity.
If you cannot trace a representative sample of figures back to source in under an hour, the constraint is the data foundation rather than the reporting effort.
Frequently Asked Questions
What is sustainability reporting software?
It is a platform that collects, centralises, analyses and discloses environmental, social and governance data in a structured, auditable form.
The distinguishing feature against general reporting tools is the audit trail linking every disclosed figure to its source.
Which frameworks do large organisations typically file to?
Most report to several simultaneously, commonly CSRD, ISSB, GRI, CDP, SASB and TCFD, with California SB 253 and SB 261 for those operating in the US market and UK SRS for those in the UK. Carbon accounting across all three scopes generally follows the Greenhouse Gas Protocol.
What level of assurance does CSRD require?
Limited assurance applies currently, with reasonable assurance scheduled to phase in. Reasonable assurance is a materially higher standard, which is why building the evidence base early is worth the effort.
What is the difference between Scope 1, 2 and 3 emissions?
Scope 1 covers direct emissions from owned or controlled sources, and Scope 2 covers indirect emissions from purchased electricity.
Scope 3 covers all other indirect emissions across the value chain, and is usually both the largest category and the hardest to collect.
Why is Scope 3 data harder to gather?
It originates outside your organisation, in suppliers’ systems and records rather than your own. That is why supplier portals and structured engagement processes matter more for Scope 3 than any internal integration does.
Can a single dataset really serve every framework?
It can, where the underlying data model supports mapping one canonical figure to multiple disclosure requirements.
What it cannot do is resolve genuine definitional differences between frameworks, which still require deliberate decisions and documentation.
Discover more from The Cameron Journal
Subscribe to get the latest posts sent to your email.




