Key Takeaways
- Selling as-is can reduce repair work, but it does not eliminate disclosure responsibilities.
- Title issues, mortgage payoffs, liens, taxes, and ownership questions should be reviewed early.
- The highest offer is not always the strongest offer once contingencies, fees, timing, and repair requests are considered.
- Net proceeds matter more than the advertised purchase price.
Table of Contents
- What Selling As-Is Really Means
- What to Check Before Selling
- Should You Make Repairs First?
- Compare Selling Options
- How to Review an Offer
- Prepare for Closing
- Taxes and Net Proceeds
- Final Checklist
Selling a house as-is can be a practical option when a property needs work, an owner is facing a tight timeline, or repairs are not financially realistic. It does not have to mean accepting the first offer that arrives. Homeowners considering cash for homes in Harrodsburg, KY should first understand the home’s condition, title status, payoff amount, and likely closing costs.
An as-is sale means the buyer agrees to purchase the property in its present condition. It does not mean that known material issues can be hidden or that a seller can ignore contract obligations. A clear process can help Kentucky sellers compare choices, avoid preventable closing delays, and focus on what they will actually receive at the end of the transaction.
Before choosing a sales path, gather the records that explain the property’s history and financial obligations. This includes the deed, recent property-tax bill, mortgage information, insurance documents, permits, repair invoices, warranties, lease documents, and homeowners association paperwork when applicable.
Owners who want to explore a direct-sale route can review information at kentuckysellnow.com, then compare any proposed terms with other available options. The important comparison is not simply speed or price. It is whether the full agreement meets the seller’s timeline, financial needs, and risk tolerance.
1. What Selling As-Is Really Means
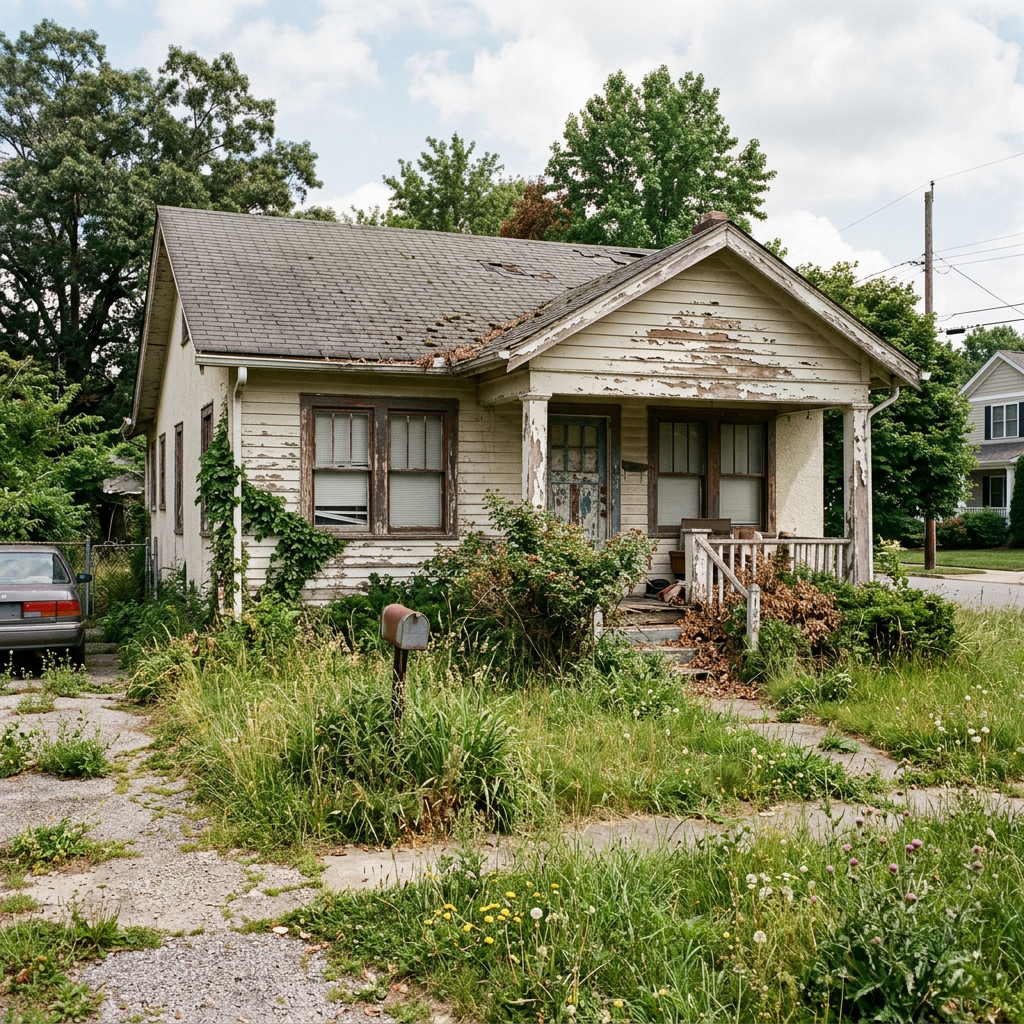
An as-is clause generally tells the buyer that the seller does not plan to make repairs or improvements before closing. For example, a buyer may agree to purchase a home with an aging roof, dated electrical fixtures, worn flooring, or visible water stains. The buyer may still request an inspection if the contract allows it, and the inspection can still affect the buyer’s decision to proceed.
As-is does not create a free pass to conceal known problems. Sellers should provide required disclosures honestly, answer direct questions carefully, and retain written records of what they shared. If there is uncertainty about a defect, estate issue, divorce-related ownership question, or prior repair, a Kentucky real estate attorney can help clarify the seller’s responsibilities.
2. What to Check Before Selling
Review Ownership and Title Records
Confirm every person named on the deed and identify anyone else who may need to sign. Common complications include a former spouse, a deceased owner’s estate, heirs, co-owners, judgment liens, unpaid property taxes, or contractor claims. A title issue can delay closing because it may need to be resolved before the buyer receives clear ownership.
Check the Mortgage Balance
Request a current payoff statement directly from the lender. The amount can be different from the balance shown on a monthly statement because it may include daily interest, late charges, or other fees. Compare the payoff, liens, taxes, and expected expenses with the likely sale proceeds. If the numbers do not cover the debt, obtain professional advice before signing an agreement.
3. Should You Make Repairs First?
Start by separating problems into three groups: safety concerns, value-related repairs, and cosmetic updates. Safety issues may include active leaks, damaged stairs, exposed wiring, or other hazards. Value-related issues can include roof wear, damaged siding, failing systems, or severely worn flooring. Cosmetic work includes paint, clutter removal, minor landscaping, and outdated fixtures.
Use a simple repair test. Get a realistic estimate that includes labor, materials, permits, and the time required. Then ask whether the work is likely to increase the sale price, prevent buyer objections, or expand the pool of potential buyers. Also account for holding costs such as utilities, insurance, property taxes, and mortgage payments. A seller does not necessarily recover every dollar spent on improvements.
4. Compare Selling Options
Option Possible Benefits Possible Trade-Offs Traditional Listing Broad exposure and access to financed buyers Showings, commissions, inspections, and a potentially longer timeline For-Sale-By-Owner More control over marketing and negotiations More responsibility for pricing, paperwork, and buyer screening Direct Cash Sale Fewer preparation steps and a simpler process Offer may reflect repair costs, risk, and the value of a faster closing Compare estimated net proceeds for each route. A conventional listing may produce a higher price but require more time and preparation. A direct sale may provide greater certainty and fewer contingencies, but convenience can be reflected in the offer amount. Request terms in writing before making a decision.
5. How to Review an Offer
Read beyond the purchase price. Review earnest money, financing, and appraisal contingencies, inspection deadlines, requested repairs or credits, closing date, possession date, title charges, and cancellation rights. An offer that is $10,000 higher may be less attractive if it has a long inspection period, uncertain financing, or significant repair demands. A lower offer with proof of funds, a realistic closing date, and fewer contingencies may create a more dependable outcome.
6. Prepare for Closing
Ask who will handle the settlement, whether it is a title company, closing attorney, or other professional. Request an itemized estimate of fees and confirm how taxes, liens, mortgage payoffs, and other obligations will be paid. The Consumer Financial Protection Bureau’s guide to title and closing services explains that title services are the largest shoppable closing cost category, including title insurance, title search, and the closing agent’s fee in most parts of the country. Comparing providers and total charges can help sellers understand the final numbers.
Wire fraud is another closing risk. Verify wiring instructions by calling a trusted phone number for the settlement provider. Do not rely on an unexpected email, a changed payment instruction, or a phone number included only in a message.
7. Consider Taxes and Net Proceeds
Final proceeds are calculated after subtracting the mortgage payoff, liens, property taxes, commissions, seller credits, and closing expenses. Tax treatment can differ for a primary residence, rental, inherited property, or investment home. Keep records of major improvements and selling expenses. The IRS guidance on tax considerations when selling a home notes that taxpayers who sell their main home for a capital gain may be able to exclude up to $250,000 of that gain from their income, and taxpayers who file a joint return with their spouse may be able to exclude up to $500,000, subject to ownership and use requirements. Tax advice is especially important when depreciation, inherited basis, or canceled debt is involved.
8. Final As-Is Sale Checklist
- Confirm every owner who must sign the deed and closing documents.
- Order a current mortgage payoff statement.
- Check for liens, judgments, unpaid taxes, and title concerns.
- Gather permits, repair records, leases, warranties, and HOA documents.
- Identify and disclose known property issues accurately.
- Get repair estimates only when they support a defined selling goal.
- Compare the net proceeds and terms of multiple selling options.
- Read every deadline, contingency, and cancellation provision before signing.
- Verify the closing provider and all payment instructions independently.
Conclusion
Selling a house as-is in Kentucky in 2026 can be a sensible decision, especially when repairs are costly or time is limited. The strongest path is the one that matches the property’s condition, the seller’s timeline, and the true net proceeds after every payoff and fee. Careful preparation before accepting an offer can make the closing process clearer and more predictable.
Discover more from The Cameron Journal
Subscribe to get the latest posts sent to your email.